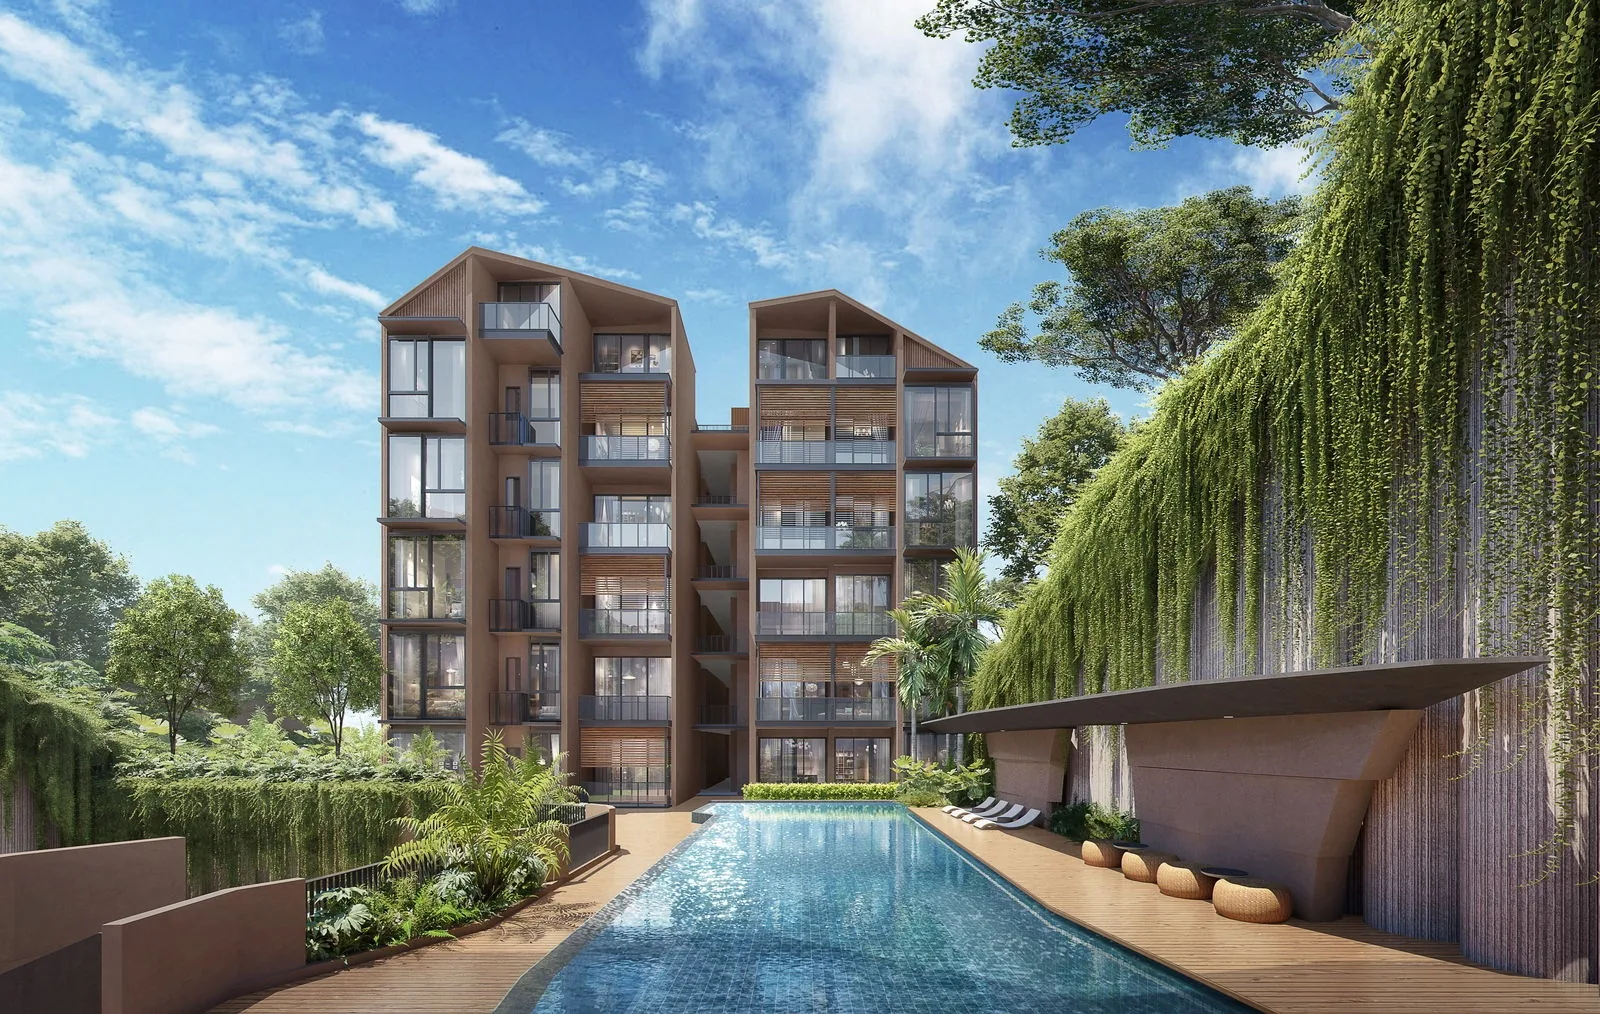
 Artist’s impression
The Hillshore Construction Timeline in Brief
The Hillshore launched in 2024, and the developer’s particulars give the expected date of vacant possession as 30 June 2027 and the expected date of legal completion as 30 June 2030. A home bought now is bought under construction and paid for in stages as the building is completed.
Building plans were approved on 1 December 2023. By the time of a purchase in late 2026, construction is well advanced, so several stages of the payment scheme may already have been certified.
From Option to Agreement at The Hillshore
A purchase starts with the option to purchase, issued by the developer against a booking fee of 5% of the price. The developer then sends the sale and purchase agreement and supporting documents to the buyer’s lawyer, and the buyer has a fixed period to sign and return it, as the Housing Developers Rules set out.
Stamp duty is due within 14 days of signing the agreement, and the next 15% of the price is paid within eight weeks of the option date. Choosing a conveyancing lawyer and obtaining an in-principle loan approval before booking keeps these weeks straightforward.
The Progressive Payment Scheme at The Hillshore
Under the Housing Developers Rules, the price is paid in fixed stages: 5% on the option to purchase, 15% at the sale and purchase agreement, then 10% at completion of the foundation, 10% for the reinforced concrete framework, 5% each for the partition walls, the roof and ceiling, the doors, windows, wiring and plumbing, and the car park, roads and drains, 25% at the Temporary Occupation Permit and the last 15% at the Certificate of Statutory Completion.
Where a stage has already been certified at the time of purchase, its instalment falls due on the timetable in the sale and purchase agreement, which usually means a larger sum early on. The Sales Concierge can set out the stages reached for a particular home.
When the Loan Starts at The Hillshore
A buyer with no other housing loan may borrow up to 75% of the price on a tenure of 30 years or less that ends by age 65. The first 25% comes from the buyer: at least 5% in cash, and the rest in cash or CPF Ordinary Account savings within CPF limits. The bank then pays each certified stage from there.
Interest is charged only on what has been drawn, so repayments start small and rise as the building nears completion. The progressive payment calculator shows the sum and the estimated monthly instalment at each stage for a price you enter.
Stamp Duty and Costs at The Hillshore
Buyer’s Stamp Duty and any Additional Buyer’s Stamp Duty are due within 14 days of signing the sale and purchase agreement, alongside the early instalments, and legal fees follow. The stamp duty page and the worked stamp duty example show how the duty is calculated.
A buyer who already owns a home should also allow for ABSD and for the lower loan limit that applies with an outstanding housing loan. Maintenance charges begin once the keys are collected, and furnishing costs follow.
From Keys to Title at The Hillshore
Vacant possession is when the keys are handed over and owners can move in or let the home; the 25% instalment at the Temporary Occupation Permit is due around then. Owners then have a defects liability period, set in the sale and purchase agreement, during which the developer makes good defects that are reported.
Legal completion follows the Certificate of Statutory Completion, when the last 15% is paid and the strata titles are issued, and the management corporation takes over the running of the estate.
How Each Stage Is Certified at The Hillshore
Each instalment after the first 20% is triggered by the project architect certifying that a stage of the building is complete. The developer then sends the buyer, or the buyer’s bank, a notice with a copy of the architect’s certificate, and payment is due within the period set by the Housing Developers Rules, usually 14 days.
Buyers financing with a loan simply forward each notice to the bank, which pays from the loan once the cash and CPF portion has been used. Keeping the notices together with the sale and purchase agreement makes the record easy to follow until the keys are collected.
Following The Hillshore Construction
The payment scheme page lists the stages, and the latest updates record each milestone. The Sales Concierge sends the current price list on request.
Showflat viewings are arranged by appointment through the Sales Concierge.
This article is general information as at the date shown and is not financial, legal or tax advice. Statutory figures are from IRAS and MAS; particulars of The Hillshore are from the developer’s brochure, unit plans and distribution chart, and dates from the developer and published reports.
Talk to The Hillshore Sales Concierge
The Sales Concierge sends the price list on request, the balance units and the e-brochure for The Hillshore. Showflat viewings are arranged by appointment through the Sales Concierge.